
Ualett
- Rating
- 4.6
- Downloads
- 500.00K
- Content Rating
- Everyone
Ualett - Screenshots
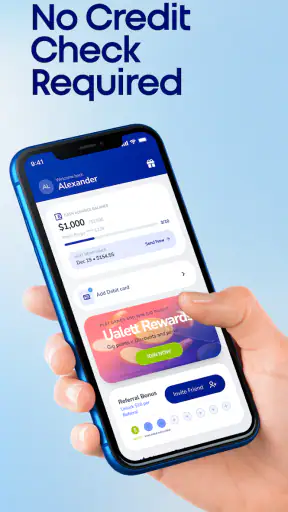
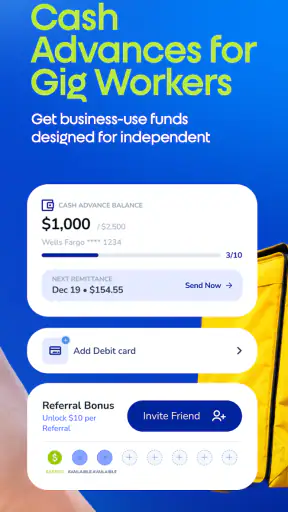
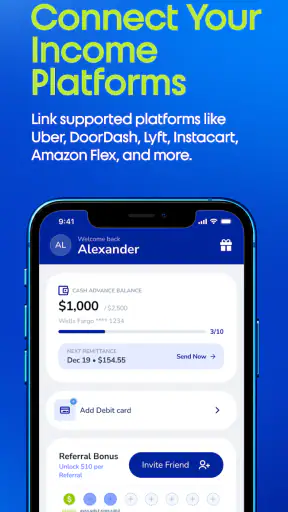
Pros
- Fast access to earned wages without waiting for payday.
- Simple application process with minimal paperwork required.
- Useful for handling unexpected bills or short-term cash needs.
- Clear repayment schedule shown before accepting an advance.
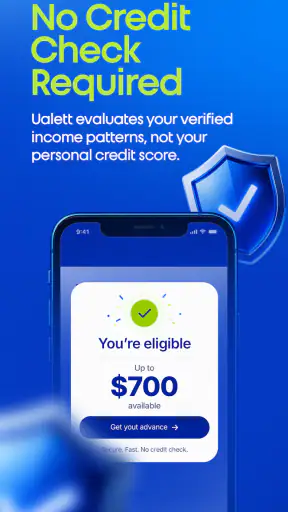
- Designed for workers with limited or no traditional credit history.
Cons
- Advance limits may be low for larger financial emergencies.
- Fees can make repeated use expensive over time.
- Eligibility depends on employment and income verification.
- Not available in every state or for every type of worker.
- Late repayment may affect future access to advances.
Ualett - Description
- App Name
- Ualett
- Package Name
- com.ualett
- Developer
- Cabicash Solutions, Inc
- Category
- Finance
- Last Updated
- Aug 21, 2018
- Version
- 2.73.0
For people who earn through driving, delivery, freelancing, or other flexible work, managing money can be harder than earning it. Income may arrive irregularly, fuel and maintenance costs can appear at the worst time, and waiting for a normal payday is not always practical. Ualett is a finance app built around that kind of working life, rather than around a traditional monthly salary.
I found its main appeal easy to understand: it is free to download and use as an app, it is aimed at gig workers, and it gives this audience a dedicated place to explore financial tools instead of forcing everything into a conventional banking routine. That does not automatically make it the right choice for everybody, though. The useful question is whether your income pattern matches the problem Ualett is trying to solve.
How Ualett fits into a gig worker’s financial routine
Ualett is a finance app from Cabicash Solutions, Inc. It has been available since August 21, 2018, and its current version is 2.73.0, with support for devices running Android 8.0 or later. Its Everyone content rating also makes it broadly accessible from an age-classification perspective.
The app has built a noticeable audience: it has passed 500K installs, with an average rating of 4.6 from around 7.6K ratings and about 1.3K written reviews. Those figures suggest that the concept has found a real audience, while still leaving room for each person to judge whether the experience fits their own work and money habits.
What matters most is the focus. Ualett is not presented as a general-purpose budgeting app for households with predictable salaries. Its identity is tied to people whose earnings may come from several shifts, platforms, clients, or short-term jobs. That focus can be valuable because the financial questions of a gig worker are different from those of someone paid on the same date every month.
For example, a delivery worker may need to think about available money after fuel, a driver may have an uneven week because of demand, and a freelancer may receive payments at different times from different sources. A tool designed with that reality in mind can feel more relevant than a standard account dashboard that treats every deposit as part of a fixed payroll cycle.
What the free price means in practical terms
The app itself is free. That makes trying it less risky than committing to a paid finance product before you know whether its workflow suits you. I would still separate free access to the app from the cost of any financial service, transaction, or optional product that might be available inside it. The download price alone should not be treated as a promise that every possible service connected with the app has no cost.
That distinction is especially important in finance. Before relying on any feature that moves money, provides access to funds, or connects to an account, I would read the terms shown at the moment of use and check any fee information carefully. A free app can still present paid services, eligibility conditions, or limits that are separate from installation.
In other words, Ualett is easy to test from a purchase standpoint, but it should not be approached casually just because there is no upfront app price. My advice is to begin with the smallest, least complicated part of the experience, understand how the service describes its costs, and only then decide whether it belongs in your regular financial routine.
A realistic day with irregular income
Imagine a driver finishing a morning shift with enough money earned to cover the day’s fuel, but not enough certainty about the evening. Instead of treating the whole balance as spendable, that driver could use Ualett as part of a broader routine: check the available financial position, keep operating expenses in mind, and decide whether accessing or managing money through a gig-worker-focused service makes sense that day.
The important insight is that the app should be used alongside a simple personal calculation, not instead of one. I would keep a separate note or spreadsheet for fuel, vehicle upkeep, taxes, and personal spending. Then I would use Ualett for the financial activity it is designed to support, while judging every decision against the real cost of completing the work.
This approach avoids a common mistake: confusing money that has arrived with money that is genuinely available. A busy day can look profitable until fuel, repairs, insurance, and tax obligations are considered. Ualett may be useful within that picture, but it cannot replace the discipline of tracking the expenses that make gig work possible.
Where the app can deliver real value
The clearest value comes from relevance. A conventional banking app may show balances and transactions perfectly well, yet still feel disconnected from the way a gig worker earns. Ualett’s dedicated positioning can make the experience easier to relate to because the starting point is flexible work rather than a fixed employer payroll.
That matters when your financial decisions are time-sensitive. A worker who is paid through several sources may value an app that feels closer to that reality than a basic account interface. It can also reduce the mental friction of searching through unrelated financial products designed for a different type of customer.
Another benefit is the low barrier to experimentation. Since the app is free, I can see whether its approach makes sense without paying simply to install it. That is particularly useful for someone who is new to gig work and still deciding which tools deserve a place in their routine.
The app’s established presence is another modest positive. Its release in 2018 and its current version show that this is not a brand-new experiment appearing without any history. The install and rating figures also indicate that other users have tried it in meaningful numbers. I would not treat popularity as proof that every experience will be smooth, but it is more reassuring than choosing an app with no visible user base at all.
I also like the possibility of making financial decisions closer to the moment they matter. Gig work often creates short gaps between earning and spending: fuel before a shift, a repair after a long day, or a personal bill arriving before the next busy period. A finance tool that acknowledges irregular cash flow can be more useful than one that assumes the user can simply wait for the next regular paycheck.
Three practical habits that improve the experience
First, I would use Ualett as part of a two-layer system. The app can handle its own role, while a separate note records the money that must be reserved for work and obligations. This prevents a convenient balance view from becoming a misleading picture of profit.
Second, I would review the cost of any financial action before confirming it, even when the app itself is free. Look for the amount involved, the timing, and any conditions displayed in the relevant screen. This habit is more valuable than simply choosing a finance app because its download button has no price.
Third, I would test the app during an ordinary work week rather than only during an emergency. An emergency can make almost any financial tool seem useful. A normal week reveals whether the navigation, timing, and overall process actually fit the way you earn and spend.
A fourth useful habit is to keep access to a backup method. I would not make one app the only route to money needed for fuel, food, or an urgent bill until I had used it long enough to understand its workflow. This is not a criticism unique to Ualett; it is sensible behavior with any financial service that becomes part of daily life.
The tradeoffs I would consider before depending on it
The first tradeoff is specialization. Ualett’s gig-worker focus is its reason to exist, but that same focus may make it less attractive to someone who wants a broad household finance system. If your main needs are detailed budgeting, long-term savings, investment tracking, or comprehensive account aggregation, a traditional banking app or dedicated budgeting tool may be a better center of your setup.
The second tradeoff is that free installation does not answer every value question. You still need to understand the terms of any specific financial service you use. In finance, the meaningful cost may be connected to an action rather than to the app download, so I would never judge the complete value proposition from the word “free” alone.
The third tradeoff is dependence on context. An app built for gig workers may be most useful when your income is genuinely variable. If you have a stable salary and only occasional side work, its specialized approach may add little compared with the banking tools you already use. In that situation, another app could be simpler because it matches your primary financial life more closely.
I would also be careful about treating a high average rating as a personal guarantee. Ualett’s 4.6 average and its community of users are encouraging, but finance experiences can vary according to work type, location, eligibility, account situation, and expectations. A driver looking for one kind of support may have a very different experience from a freelancer looking for another.
There is also a practical learning curve whenever money is managed through a new service. Even if the interface is straightforward, you need to understand what each balance or status means before making it part of a time-sensitive decision. I would rather spend a few minutes learning the process than assume that a familiar-looking screen works exactly like my bank’s app.
Who is most likely to get value from Ualett?
I see the strongest fit for drivers, couriers, independent contractors, and other workers whose earnings do not follow a dependable payroll calendar. It is also a sensible candidate for someone who wants to try a gig-worker-oriented finance app without paying an upfront download fee.
It may be especially useful if your current bank app feels too generic for the way you work. The value is not merely having another place to look at money; it is having a product whose central audience understands that income can arrive in uneven bursts and that work-related expenses can come before personal spending.
New gig workers may also appreciate the chance to explore a focused tool while building better habits. I would recommend pairing it with a basic expense record from the first day. That way, the app becomes part of a deliberate system instead of a quick answer to every cash-flow problem.
On the other hand, I would tell someone with a stable salary and no meaningful gig income to think twice. If your main goal is household budgeting, shared finances, savings targets, or investment management, a general finance platform may offer a more complete fit. Ualett’s focus becomes less compelling when the problem it addresses is not central to your life.
I would also advise caution for anyone who expects an app to solve an income shortage by itself. A finance app can organize access and decisions, but it cannot make an unprofitable work pattern profitable. If fuel, maintenance, taxes, and personal expenses already consume most of what you earn, the right answer may be changing the work plan or seeking professional financial guidance rather than adding another app.
My verdict after weighing convenience against responsibility
Ualett is worth trying if gig work is the main reason your finances feel irregular. Its free app access lowers the barrier to testing it, its purpose is clearly aimed at flexible workers, and its long-running presence and user response make it a credible option to investigate.
My recommendation comes with a boundary: I would use it as one part of a financial routine, not as a substitute for budgeting or careful checking. Track the costs of earning, review the terms of any service before using it, and keep a backup way to manage essential money until you are comfortable with the process.
For the right user, that balance makes sense. A courier managing uneven weekly income may find more relevance here than in a standard banking app. A salaried user looking for a complete money-management suite probably will not. The app’s value comes from matching its specialized purpose to your actual work, not from installing it simply because it is free.
Overall, I would recommend giving Ualett a controlled trial to gig workers who want a finance tool built with their income pattern in mind. I would skip it if your needs are mainly long-term budgeting or broad banking management. That is a fair result for a focused finance app: useful when the problem matches, unnecessary when it does not.
FAQ
What is Ualett and what can I use it for?
Ualett is a digital financial service designed to help users manage everyday money tasks through a mobile application. Depending on your location and eligibility, it may provide features such as receiving payments, managing funds, viewing transaction activity, and accessing other financial tools. Available services can vary by country, so review the official terms and supported features before creating an account.
Who can open a Ualett account, and what information is required?
Account availability depends on your country, age, identity, and Ualett’s current eligibility requirements. During registration, you may be asked to provide personal details such as your legal name, phone number, email address, date of birth, and identification documents. Verification is part of the onboarding process, and approval may not be immediate if additional information is required.
Is Ualett safe to use for storing or managing money?
Ualett uses account security and identity-verification procedures intended to protect users and reduce unauthorized activity. However, no financial application is completely risk-free. Before depositing or receiving money, check how your account is protected, whether funds are held by a regulated financial institution, what recovery options are available, and how suspicious transactions should be reported.
Does Ualett charge fees for its services?
Fees may apply depending on the feature you use, the transaction type, your location, and the payment method involved. Possible charges can include transfer, withdrawal, card, currency-conversion, or service fees. The exact pricing should be confirmed inside the app or on Ualett’s official website, since fees and limits may change over time.
What should I do if I cannot access my Ualett account or a transaction is missing?
If you have trouble signing in, first confirm that you are using the correct phone number or email and the latest version of the app. Use the official recovery process rather than sharing passwords or verification codes with anyone. For missing, delayed, or unauthorized transactions, save relevant details and contact Ualett support through its verified in-app or website channels.


